[ Infrastructure ]
Who Wins and Who Pays: The AA Fee Model's Consequences for Lenders, Aggregators, Banks and TSPs
The questions everyone is asking about the 1 November AA rate card, answered by stakeholder, including the cost-per-approved-loan arithmetic, why aggregator consolidation now follows, and what is still unanswered.
10 min read · 15 October 2026
Contents
Lenders pay the new Account Aggregator fee and borrowers pay nothing. Banks gain a revenue line tied to delivery quality, aggregators gain a fixed share but lose coverage and price as differentiators, and technology service providers lose their cut entirely. For lenders the number that matters is not the fee per application but the fee per approved loan, which can be three to four times higher.
India's Account Aggregator network spent five years without a price. From 1 November 2026 it has a rate card, and the RBI expects interoperability among aggregators by 31 December. Between them these two changes redistribute money, remove the main source of differentiation between aggregators, and quietly change how a lender should design a loan application funnel.
This covers the questions being asked across the ecosystem, grouped by who is asking them.
First, what actually changed
The detail is in our breakdown of the AA price list. In brief:
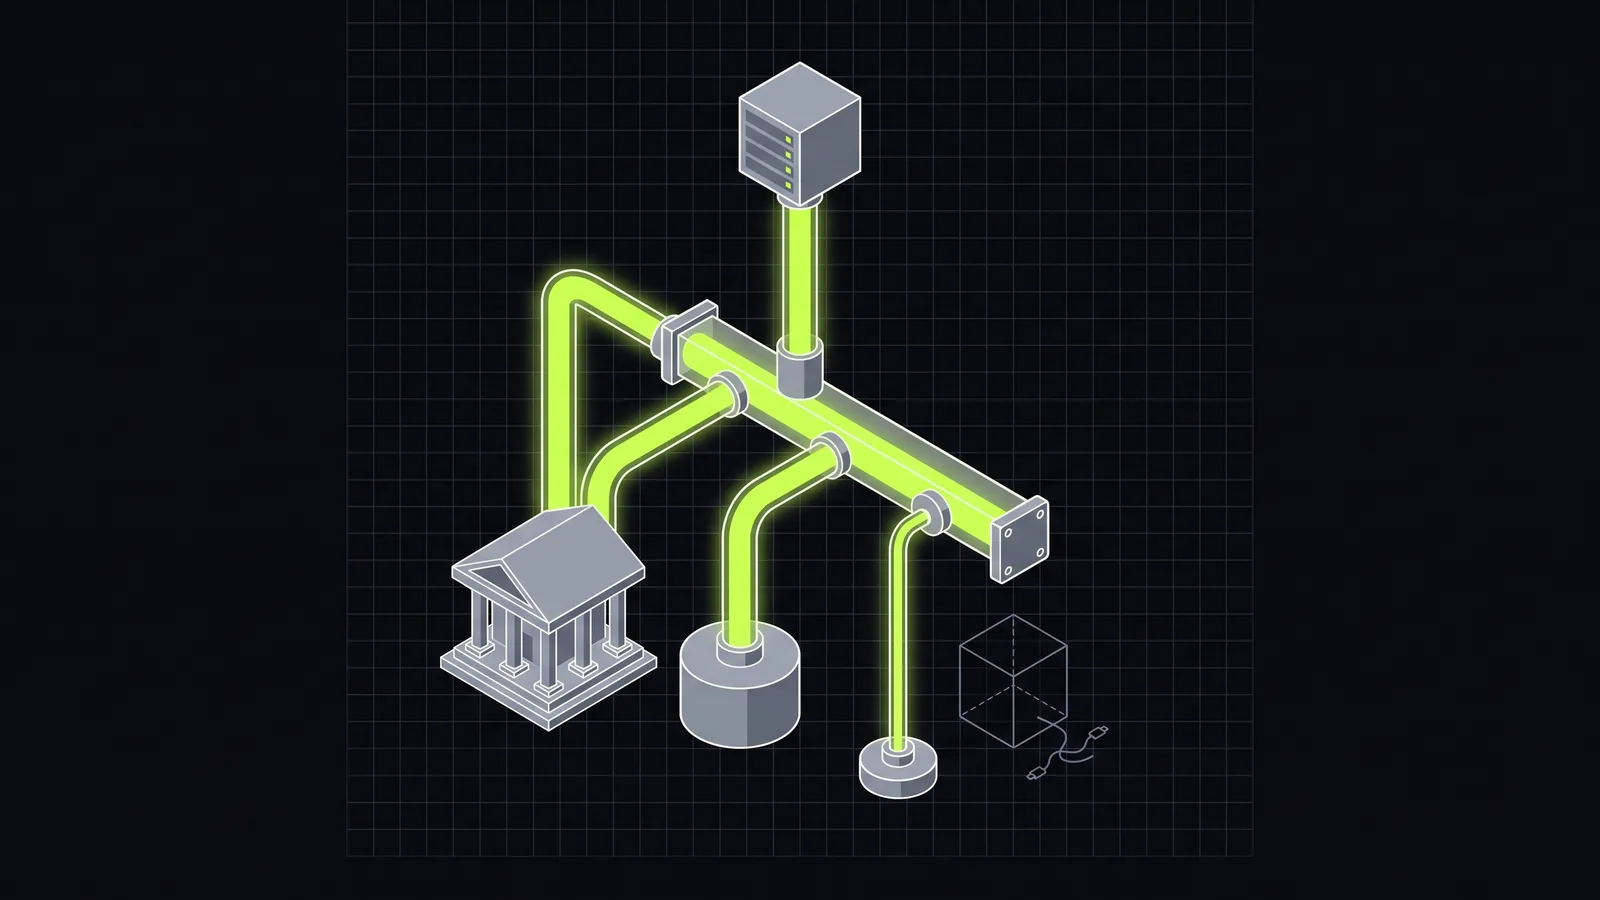
- 1 November 2026. A standard fee replaces bilateral commercial arrangements. On the benchmark of a seven-month bank statement, the lender pays roughly ₹5.88 to ₹6.55 per bank account successfully shared, varying with the number of months requested. Of that, ₹2.80 goes to the data provider and ₹0.40 to Sahamati, with the remainder to the aggregator. It is termed a DPI utility fee.
- 1 December 2026. Data providers start earning their share, conditional on a minimum monthly delivery success rate beginning at 80% and rising.
- 31 December 2026. Interoperability among all NBFC account aggregators is expected to be implemented, under an RBI policy announcement of 7 October 2026.
Who issued the pricing? Sahamati, not the RBI, although some early coverage attributed it to the regulator. The fee is set by a Sahamati circular, reported by Business Standard on 13 October and not yet published. Sahamati issues it as the self-regulatory organisation the RBI recognised on 5 June 2026. Interoperability is the RBI's own decision, in its statement of 7 October. The distinction matters for how each is enforced, so get the primary documents before building a position on either.
The question asked first, by everyone
Does the borrower pay?
No. Under the circular, entities in the network cannot charge customers directly for sharing their own data. The financial information user, the lender, pays a single bill to the aggregator, which distributes the shares.
Then why is there a fee on public digital infrastructure at all?
Because somebody has been carrying the cost. Data providers built and ran integrations, served two-factor authentication, maintained consent dashboards and absorbed the cybersecurity obligations, and received nothing. Sahamati ran on donations for seven years. Aggregators have struggled to reach profitability. Infrastructure with no revenue model does not get maintained, and the AA network was approaching that limit.
This is worth stating plainly rather than defensively: the ecosystem has decided that data free at the margin had an owner who was paying for it, and that the party extracting commercial value should pay instead. Whether ₹6 per account is the right number is a fair debate. Whether the number should have been zero forever is not.
For lenders and fintech lenders
How much will this actually cost us?
The per-application figure is modest. Two accounts at roughly ₹6 is about ₹12 per applicant; 5,000 applications a month is in the order of ₹60,000.
But model cost per approved loan, not cost per application. This is the number that matters and almost nobody is computing it.
You pay on every successful fetch, including for applicants you decline. At a 30% approval rate, 100 fetches produce 30 booked loans, so the data cost per booked loan is 3.3 times the per-application cost. At ₹12 per application that is roughly ₹40 per approved loan.
| Loan | Approval rate | Data cost per approved loan | Share of principal |
|---|---|---|---|
| ₹3 lakh business loan | 30% | about ₹40 | 0.01% |
| ₹50,000 personal loan | 30% | about ₹40 | 0.08% |
| ₹8,000 small-ticket consumer loan | 25% | about ₹48 | 0.6% |
Two bank accounts per applicant at roughly ₹6 each.
Against a ₹3 lakh business loan, ₹40 is immaterial. Against a ₹50,000 personal loan it is still comfortable. Against an ₹8,000 small-ticket consumer loan at a 25% approval rate, the data cost approaches 0.6% of principal before any other acquisition expense, which on thin margins is a real line item.
Does this kill AA for small-ticket lending?
Not on its own, but it changes the sequencing. The honest answer depends on approval rate and ticket size together, and the lenders most affected are those running low approval rates on small tickets: exactly the high-funnel, high-rejection digital lending models.
So should we change our application flow?
This is the most consequential practical answer in the whole change. Previously, fetching AA data early for every applicant cost nothing at the margin, so many flows did exactly that. Now there is an economic reason to pre-qualify before fetching: run the cheap checks first (bureau pull, policy knockouts, declared income plausibility) and request bank data only for applicants who survive them.
That is better funnel design regardless of price. It also aligns with DPDP data minimisation, since you stop collecting detailed financial data on people you were never going to approve. Three pressures pointing the same way.
Should we reduce the data range we request?
Review the default, do not reduce reflexively. Pricing varies with months requested, so a twenty-four-month default will cost more than a twelve-month one. But twelve months is the practical floor for business lending, because anything shorter cannot separate a seasonal trough from a decline, and a cheaper pull that produces a wrong answer is not a saving. Trim habitual over-collection; do not trim below what the assessment needs.
Will AA now cost more than collecting PDFs?
Very unlikely. Manual statement collection carries application drop-off, days of turnaround, and the handling cost of files that fail to parse and route to manual review, where tamper controls do not run. A few rupees per account does not approach that.
Do we pay for failed fetches?
Reporting describes the fee as payable on data successfully shared, which implies not. The precise treatment of partial fetches and timeouts is not established in public reporting. Confirm it in your aggregator contract.
What about monitoring?
Monthly refresh across a live book turns monitoring frequency into a budgeted decision rather than a default, and makes risk-tiered and event-triggered refresh a financial argument as well as an analytical one. The monitoring cost arithmetic is worked through here, including the open question of whether each fetch under a recurring consent is charged separately.
For account aggregators
Does this finally make aggregators profitable?
It gives them a defined, network-wide revenue share on every successful fetch, at a volume Sahamati's dashboard puts at about 380 million data deliveries in September 2026. That is a materially better position than negotiating bilaterally against lenders and technology intermediaries. Whether it produces profitability depends on each aggregator's share of that volume, which Sahamati does not publish by aggregator. Aggregators can also still charge lenders separately for value-added services on top of the standard fee.
What do aggregators compete on now?
This is the structural consequence, and it deserves more attention than the pricing.
Until now, aggregators differentiated substantially on coverage: which data providers they had onboarded. Interoperability is meant to remove that from 31 December. Fee standardisation removes price. What remains is reliability, latency, success rate, support quality and developer experience.
Does that mean consolidation?
It is hard to see how not. Seventeen operational aggregators, coverage neutralised as a differentiator, and price fixed by circular. Competition narrows to operational quality in a market where the smallest participants have the least volume over which to amortise that quality.
For a lender the practical read is the inverse: multi-aggregator arrangements maintained purely to reach different banks become redundant once interoperability is live, and worth reviewing against contracts signed on the old assumption.
For technology service providers
Are TSPs finished?
Their previous commercial position is. Under the new model TSPs receive no share of the standard fee and sit outside its distribution. Industry participants expect margins to compress, and aggregators with their own technology arms may offer the integration layer to lenders at no charge.
One TSP founder quoted in the reporting framed the objection as a fundamental incentive misalignment with no benchmarking on costs, which is a reasonable argument to put. It is also an argument made by the party losing the fee share, and aggregator executives in the same report answered that TSPs had been unreasonably profitable compared with AAs. Both sides have a point, and both have an interest.
What is left for them?
Work that is genuinely theirs rather than intermediation rent: analysis on top of the data, decisioning, workflow, orchestration across multiple data sources, and anything that needs building rather than passing through. The pipe is becoming a regulated utility with fixed pricing; value moves to what sits on either end of it.
What should lenders using a TSP do?
Establish two things. What you are now paying the TSP for, given fee distribution excludes them. And whether your aggregator provides the same integration layer directly.
For banks and other data providers
Why would a bank care about ₹2.80?
Because it was previously zero while the cost was not. The share is small per fetch and meaningful at scale, and more importantly it converts data provision from a pure compliance cost into a revenue line with a business owner attached.
What is the success rate condition?
Providers earn their share only on meeting a minimum monthly delivery success rate: 80% from 1 December, rising subsequently. This is the first time data quality in the AA network has had money attached to it, and it targets the ecosystem's most persistent complaint.
Will data quality actually improve?
Fetch reliability, probably. The open question is narration quality, which is the field everything downstream depends on. A success-rate floor measures whether data arrived, not whether the transaction narration that arrived was rich enough to categorise. Those are different properties, and only the first is being priced. Worth instrumenting both on your own traffic from December: success rate by provider, and narration completeness by provider.
For borrowers
Does this cost the customer anything?
Not directly. The circular does not permit network entities to charge customers for sharing their own data.
Does anything improve for them?
Two things, both from interoperability rather than pricing. Fewer failed consent journeys, because the RBI's stated aim is that customers can share information through any aggregator of their choice, so a borrower should no longer be turned away for being registered with a different aggregator than their lender uses. And less need to register with multiple aggregators to cover accounts at different institutions.
The friction being removed is real. A lender signs with one or two aggregators; the borrower may hold accounts at institutions those aggregators never onboarded; the consent fails for reasons that have nothing to do with the borrower's willingness to share.
What is still unanswered
Worth listing explicitly, because confident answers are circulating on points the public reporting does not settle:
- Whether each fetch under a recurring consent is charged separately, or recurring consents are priced differently. This swings monitoring economics substantially.
- The treatment of failed, partial and timed-out fetches in practice.
- Whether volume tiers or caps exist for high-volume users.
- How non-bank data types are priced (insurance, depository holdings, GST, NPS), where the seven-month bank statement benchmark does not apply.
- The schedule for the rising success-rate threshold beyond the initial 80%.
- How interoperability is technically implemented, which determines how much work lands on lenders versus aggregators before 31 December. Sahamati's chief executive has called the topology a technical design choice, and specifications had not been issued by mid October.
- How aggregators settle with each other when a fetch crosses from one aggregator's network to another's.
Get these from your aggregator and from the primary circular, not from commentary.
The honest tension
There is a real argument that putting a price on digital public infrastructure slows adoption, and it should not be waved away. India's experience with zero MDR on UPI cuts both ways: it drove extraordinary adoption, and it left a payment rail whose operators spent years arguing about who funds its maintenance.
AA is choosing the other path: a priced utility with a defined revenue split, paid by the commercial party rather than the citizen. The cost is that some marginal use cases become uneconomic, and small-ticket high-rejection lending models are where that bites first. The benefit is a network whose participants have a reason to keep it working.
Reasonable people will disagree about the rate. The structure, where the party extracting commercial value pays and the individual whose data it is does not, is harder to argue with.
What none of this changes
Every change above improves the pipe: cheaper to run, more reliable, reachable through any aggregator. None of it touches what arrives through it.
A date, an amount, a direction and a narration string still have to be read as an EMI or a supplier payment, a sale or a loan disbursal or a transfer between the borrower's own accounts. Tools still disagree on that reading, by 12.5 percentage points on the same 200,001 transactions. Cheaper data means more of it, which makes interpretation the binding constraint sooner, not later.
Frequently asked questions
How does the AA fee affect small-ticket lending? Model cost per approved loan rather than per application, since the fee is paid on declined applicants too. At a 30% approval rate the per-booked-loan cost is over three times the per-application cost, which matters most for low-approval, small-ticket digital lending. The practical response is to pre-qualify with cheaper checks before requesting bank data.
Does the borrower pay anything under the new AA fee model? No. The lender pays, in a single bill to the aggregator. The Sahamati circular does not permit network entities to charge customers directly for sharing their own data.
What is the DPI utility fee? The term used for this standardised AA charge, framed as funding the network's compliance and infrastructure costs (two-factor authentication, consent dashboards and cybersecurity) which participants previously absorbed without compensation.
Did the RBI or Sahamati issue the AA pricing circular? Sahamati, which the RBI recognised as the self-regulatory organisation for the Account Aggregator ecosystem on 5 June 2026. Some early coverage attributed the pricing to the RBI. The interoperability timeline, by contrast, is the RBI's own, announced on 7 October 2026.
Will the number of account aggregators fall? Consolidation is the likely direction. Interoperability removes coverage as a differentiator and the standard fee removes price, so competition among the seventeen operational aggregators narrows to reliability and service, in a market where the smallest players have the least volume to fund either.
What happens to TSPs under the new AA fee model? They receive no share of the standard fee and sit outside its distribution, so intermediation margins are expected to compress. Value shifts toward analysis, decisioning and orchestration rather than passing data through.
Will the new fee model improve AA data quality? Data providers earn their share only on meeting a minimum monthly success rate starting at 80% from 1 December 2026, which should improve fetch reliability. Whether transaction narration quality improves is a separate question, since the condition measures delivery rather than content.
Fee figures are from the Sahamati circular as reported by Business Standard on 13 October 2026; the circular itself has not been published. The interoperability timeline is from the RBI statement of 7 October 2026. Verify against the primary documents before acting on either. Fiscus ingests AA-delivered data natively and applies identical analysis to AA and document paths. Book a parallel evaluation.
Written by
Zeus DhanbhooraZeus Dhanbhoora is the CEO of BridgeUp Tech, the company behind Fiscus. He previously co-founded Bacferim Technologies and was an associate at the law firm Bharucha & Partners. He writes the Fiscus credit desk blog on benchmarks, fraud detection and credit underwriting methods.