[ Credit Risk ]
Your Portfolio Report Is Lagging Indicators, Aggregated
DPD-based vintage curves tell you about originations from three quarters ago, which is how lenders keep writing into a bad vintage. Banking-derived cohort signals readable at month two, and the correlated exposure no bureau will show you.
9 min read · 15 October 2026
Contents
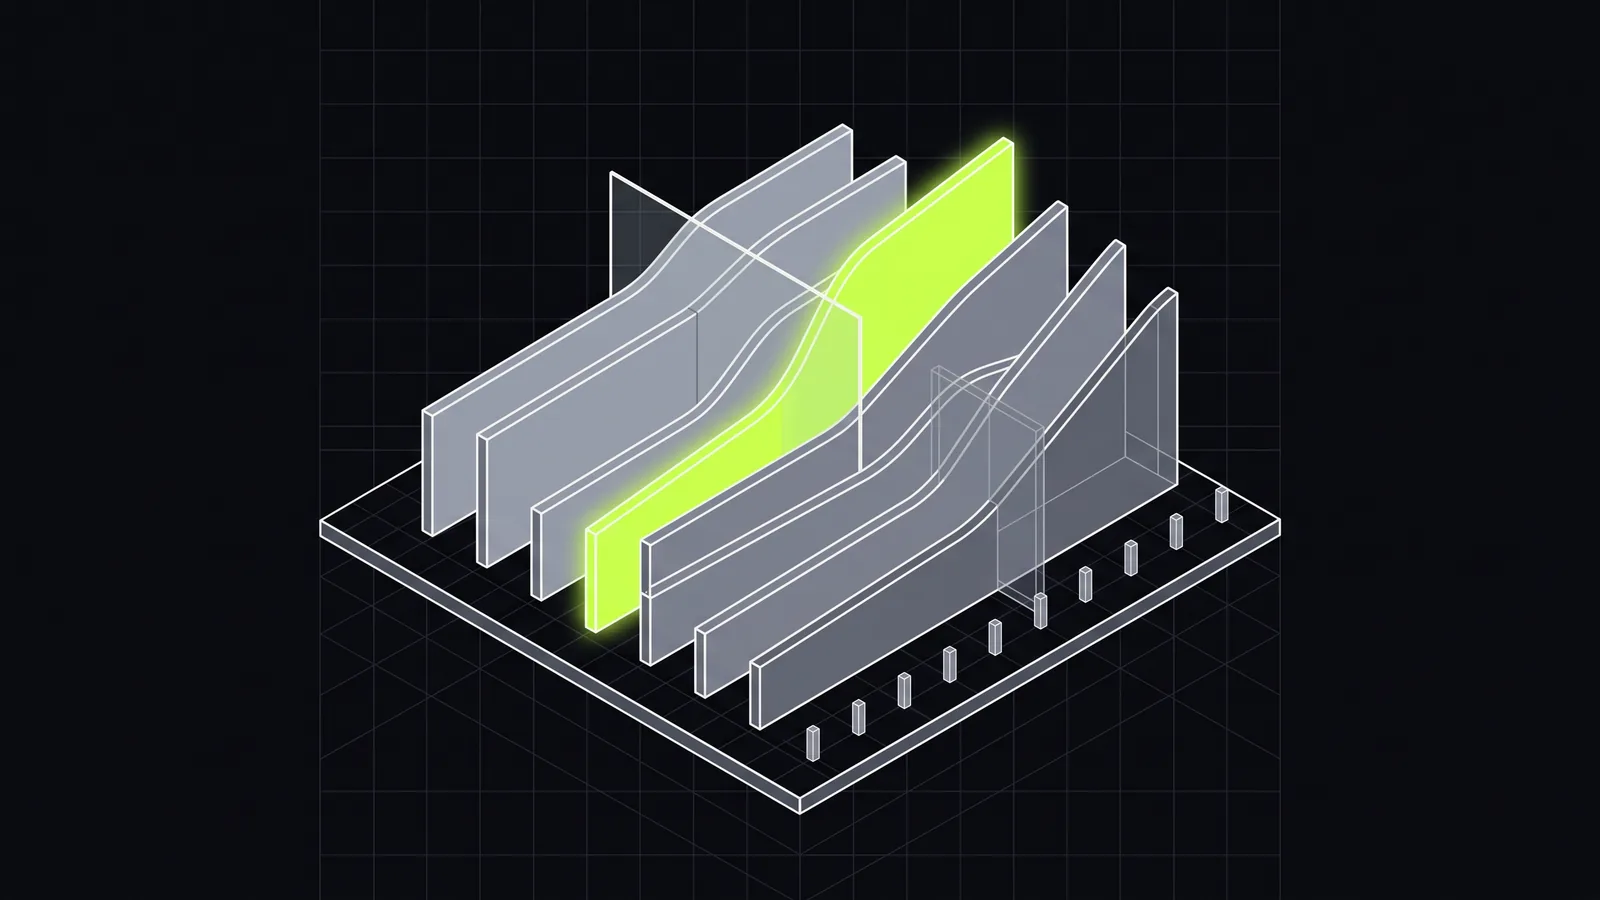
Vintage analysis compares loans by the month they were originated, plotting a performance measure against months on book. Built on days past due, it reports a bad cohort two to three quarters after origination, by which time the same policy has written several more. Built on banking signals such as throughput against baseline and new obligations, the same chart separates cohorts within the first months after disbursal.
Most portfolio risk reporting is built from days past due, bucket migration and bureau refreshes. Each of those is a lagging indicator. Aggregating lagging indicators does not produce a leading one. It produces a lagging indicator with better error bars.
The practical effect is a detection lag of two to three quarters between a change in origination quality and a visible change in portfolio metrics. That lag is not a reporting inconvenience. It is the mechanism by which lenders keep writing into a vintage that has already gone wrong.
The arithmetic of detection lag
Consider an illustrative sequence for a cohort originated in April.
Deterioration begins in the borrower's account around month two or three. EMI delay days start lengthening around month four. First bounces appear around month five. The first missed instalment, and with it the first days past due, arrives around month six or seven. Bureau data reflects it within a week or two, since lenders have reported to credit bureaus weekly since July 2026. Your quarterly vintage review picks it up at the following reporting cycle, call it month nine or ten.
Faster bureau reporting does not close the gap. It shortens the last step of the chain, while the long wait sits upstream, between the account showing strain and the borrower actually missing a payment.
In the meantime you have originated May, June, July, August and September under the same policy, the same scorecard cut-off, the same channel mix and the same exception practice. By the time the April cohort is visibly bad, five more cohorts carrying the same flaw are on the book, and the two most recent are too young to show anything at all.
The cost of a bad vintage is roughly proportional to how long you keep originating into it. Every month of detection lag is a month of additional exposure written on a known-bad basis that you do not yet know is bad.
This is why portfolio monitoring built on banking data is a different proposition from the same data used for single-borrower monitoring. Individually it catches a borrower. In aggregate it catches a policy.
What conventional vintage analysis does and does not give you
Standard vintage analysis plots a performance measure (30+ DPD, 90+ DPD, roll rates) against months on book, one curve per origination cohort. It is the right structure, and the structure is not the problem.
The problem is the measure. DPD at month three is near zero for every cohort, good and bad alike, because it takes that long for a struggling borrower to actually miss a payment. The curves only separate once the damage has occurred. A vintage chart is an accurate record of what happened and a poor instrument for intervening.
Keep the structure. Change the measure to something that moves earlier.
Cohort signals readable at month two
Every signal in the early warning sequence can be aggregated to cohort level and plotted against months on book. Six carry the most information.
Facility utilisation drift. Mean and distribution of utilisation against each borrower's own baseline at origination. A cohort whose utilisation distribution shifts upward in its first quarter is absorbing stress with credit.
Throughput against baseline. Share of the cohort whose monthly credit throughput has fallen more than a defined threshold below its own origination baseline, seasonality adjusted. This is the cleanest single measure of whether a cohort's businesses are performing as underwritten.
Obligation accretion. Share of the cohort that has acquired new recurring EMI debits since origination, and how many of those appear on the bureau. A cohort borrowing elsewhere within three months of disbursal was underwritten on an obligation picture that no longer holds. The portion absent from the bureau is the part your refresh will not catch.
Related-party dependence. Share of the cohort whose promoter or group inflows have risen as a proportion of total credits. Promoters funding operations is a mid-sequence signal, and at cohort level it is a strong read on whether the segment is under pressure.
Delay-day creep. Mean days between obligation due date and actual payment, by month on book. This moves before any bounce and is discarded by systems that record whether an EMI was paid rather than when.
Zero-balance day count. Mean and distribution, read from end-of-day balances. A rising count across a cohort indicates thinning liquidity before any failure.
| Signal | Cohort level measure | What a rising value says |
|---|---|---|
| Utilisation drift | Mean utilisation against each borrower's own origination baseline | The cohort is absorbing stress with credit |
| Throughput against baseline | Share with credits more than a set threshold below baseline, seasonality adjusted | The businesses are not performing as underwritten |
| Obligation accretion | Share with new recurring EMIs, split bureau-visible and bureau-absent | The obligation picture at sanction no longer holds |
| Related-party dependence | Share with promoter or group inflows rising as a proportion of credits | Promoters are funding operations |
| Delay-day creep | Mean days from due date to payment, by month on book | Payment stress before any bounce |
| Zero-balance days | Mean and distribution of days at or near zero | Liquidity is thinning |
Each of these is observable from month one or two of a loan's life, which means a cohort comparison is possible while you are still originating the next one.
The comparison that becomes useful
Once the measure moves early, the normal vintage comparison starts answering questions you can act on.
Policy changes. You relaxed a FOIR threshold in July. Compare the July cohort against June at the same months on book on throughput deterioration and obligation accretion. You have an answer in two months rather than three quarters.
Channel quality. Same cohort, split by sourcing channel: direct against DSA against digital. Channels differ in borrower quality in ways that scorecards frequently do not capture, and banking-derived drift surfaces it earlier than delinquency does.
Geography and segment expansion. A lender moving into new markets is originating against a thinner historical base, and semi-urban and rural markets now account for more than 58% of NBFC loans by volume, according to FIDC and TransUnion CIBIL. Reading those cohorts on early signals rather than waiting for DPD is the difference between a calibrated expansion and an uncontrolled one.
Exception performance. Files approved with policy deviations, as a cohort of their own, against the clean cohort. Most institutions never measure this, which means deviation practice is governed by judgement with no feedback loop attached.
Scorecard band validation. Whether the bands actually separate on early banking signals. This matters most for thin-file and new-to-credit cohorts, where a score was assigned on limited evidence and the first months of observed conduct carry more weight than the score did.
Correlated exposure nobody is looking at
This is the finding available only at portfolio level, and it is invisible to every conventional risk system.
Single-borrower analysis establishes counterparty concentration: this borrower depends on that buyer for 38% of receipts. Useful, and standard.
Run counterparty resolution across the whole book and a different question becomes answerable: how many of your borrowers depend on the same counterparty?
Twenty SME borrowers in your portfolio, each individually well diversified by their own concentration metric, may nevertheless all sit in the same supply chain feeding one large buyer. That buyer delaying payments by 45 days is a simultaneous liquidity event across twenty exposures. Each file looks fine. The portfolio has a concentration it has never measured.
No bureau will show this. No DPD report will show it. No single-borrower analysis will show it, because each borrower genuinely is diversified relative to their own receipts. It only appears when counterparties are resolved and aggregated across the book. That requires transactions to carry an identified counterparty rather than a narration string, the capability that varies most between tools and that we measured across 200,001 transactions.
Three portfolio views worth building from it:
- Shared-counterparty exposure. Total outstanding across borrowers whose receipts depend materially on any single counterparty.
- Supply-chain clusters. Groups of borrowers linked by common buyers or suppliers, which often map to a sector or a geography more precisely than your own segment codes do.
- Counterparty deterioration as a portfolio signal. When a counterparty common to several borrowers starts paying later, that is an early signal across every exposure connected to it, detectable from the receipt timing in your own borrowers' accounts before any of them reports difficulty.
The same logic extends to related-party structures. Two borrowers sharing a promoter, or transacting with each other through group entities, are one exposure in substance regardless of how the files were underwritten, and related-party identification across the book is what surfaces it.
Where this gets overstated
Honest limits, because a portfolio analytics argument is easy to oversell.
Consent coverage determines what you can see. Continuous reading requires either a recurring Account Aggregator consent taken at origination with a duration covering tenure, or a banking relationship that gives you the account. Sahamati's loan monitoring consent template allows at most five fetches a month and runs for up to five years or the loan tenure, whichever is shorter, so a longer loan needs a fresh consent part way through. A portfolio where half the cohort is unobservable produces a biased cohort signal, and the bias is unlikely to be random: borrowers who decline continued visibility are not a neutral subset. The consent design question is therefore a portfolio analytics prerequisite, not an origination detail.
Benign-period calibration. Thresholds for what counts as adverse drift are being set on recent data. Indian retail and MSME delinquency has been favourable (90+ day balance-level delinquency on NBFC portfolios fell from 2.7% in June 2019 to 1.1% in June 2026, per the same FIDC and TransUnion CIBIL report), and thresholds calibrated on that period have not been tested through a downturn. Treat them as provisional.
Survivorship. Cohort signals computed on live accounts exclude those already written off or closed, which flatters later months on book unless handled explicitly.
Cash invisibility. Cohorts concentrated in cash-heavy segments are partially observable at best, and the observable portion is not a random sample of their activity.
Correlation is not causation at cohort level either. A cohort showing drift may reflect a sector event rather than an origination failure, and distinguishing the two requires looking outside the portfolio.
A minimum viable version
If none of this exists today, the sequence that gets most of the value:
- Pick one measure: share of cohort with throughput more than 20% below its own origination baseline, seasonality adjusted. One number, per cohort, per month on book.
- Plot it against months on book, one curve per origination month, alongside the existing DPD vintage chart.
- Split by one dimension that you actually control. Channel is usually the most actionable; policy exception status is the most neglected.
- Add obligation accretion as the second measure, separating bureau-visible from bureau-absent.
- Then build the counterparty overlap view, which is the highest-value item and the one requiring the most underlying capability.
Steps one and two are a reporting exercise on data most lenders with monitoring consent already hold. They will separate cohorts months before the DPD curves do, which is the entire point.
Frequently asked questions
What is vintage analysis in lending? Plotting a performance measure against months on book, one curve per origination cohort, to compare the quality of loans written in different periods. Conventionally the measure is delinquency, which only separates cohorts once the damage has occurred.
What does months on book mean? The number of months since a loan was disbursed. Vintage analysis aligns every cohort on months on book rather than calendar month, so a loan written in April and one written in July are compared at the same age.
Why is DPD-based portfolio reporting considered lagging? Borrower deterioration becomes visible in banking behaviour around month two or three, while the first missed instalment typically comes months later. A quarterly review on DPD therefore reports on originations from two to three quarters earlier, during which the same policy has continued to originate.
Which banking signals work at cohort level? Facility utilisation drift against each borrower's baseline, throughput deterioration against origination baseline, new obligation accretion separated into bureau-visible and bureau-absent, rising related-party dependence, lengthening delay days, and zero-balance day counts. All are observable within the first months of a loan's life.
What is correlated counterparty exposure? Multiple borrowers in a portfolio depending on the same buyer or supplier, so that one counterparty's payment delay creates a simultaneous liquidity event across several exposures. Each borrower may be well diversified by their own concentration metric, which is why it is invisible without resolving counterparties across the whole book.
Can you run cohort monitoring without Account Aggregator consent? Only for borrowers whose accounts you can see some other way, such as those who bank with you. Continuous reading needs either a recurring consent taken at origination with a duration covering the loan tenure (Sahamati's loan monitoring template caps it at five years), or the account relationship itself. A cohort where many borrowers are unobservable produces a biased signal, because borrowers who decline continued visibility are not a random subset.
What is the fastest way to start measuring origination quality earlier? Compute the share of each cohort whose monthly credit throughput has fallen materially below its own origination baseline, plot it against months on book alongside the existing delinquency vintage curves, and split it by sourcing channel.
Fiscus reads borrower banking continuously across a portfolio, with counterparties resolved so exposure can be aggregated by common buyer, supplier and related party. Book a parallel evaluation on a segment of your live book.
Written by
Zeus DhanbhooraZeus Dhanbhoora is the CEO of BridgeUp Tech, the company behind Fiscus. He previously co-founded Bacferim Technologies and was an associate at the law firm Bharucha & Partners. He writes the Fiscus credit desk blog on benchmarks, fraud detection and credit underwriting methods.